Medical Invoice: What It Means, What's on It and How to Check It
A medical invoice is the bill a healthcare provider, such as a doctor’s office, clinic, hospital, lab or therapist, sends to request payment for care. It lists each service with its date, a billing code and the charge, subtracts what insurance paid or adjusted, and shows how much the patient owes. In medical billing, the invoice is the patient-facing bill; the insurer is billed separately with a claim.
This guide explains what is on a medical invoice, how to read and check one, how to tell a real bill from a fake, and how providers can create clear invoices.
What is on a medical invoice
Most medical invoices, also called patient statements, have the same parts:
- Provider details: practice or hospital name, address, billing phone number and often a tax ID.
- Patient and account: your name, date of birth or account number, and the insurance on file.
- Invoice number, statement date and due date.
- Date of service for each visit, test or procedure.
- Service description and codes. Procedures use CPT codes, maintained by the American Medical Association, or HCPCS Level II codes for supplies and services CPT does not cover. Diagnoses use ICD-10-CM codes.
- Charges: the provider’s price for each service.
- Insurance payments and adjustments: what your plan paid, and amounts written off under the plan’s contract.
- Patient responsibility: what is left for you, such as a copay, coinsurance or the part of your deductible not yet met.
- How to pay and whom to call with questions.
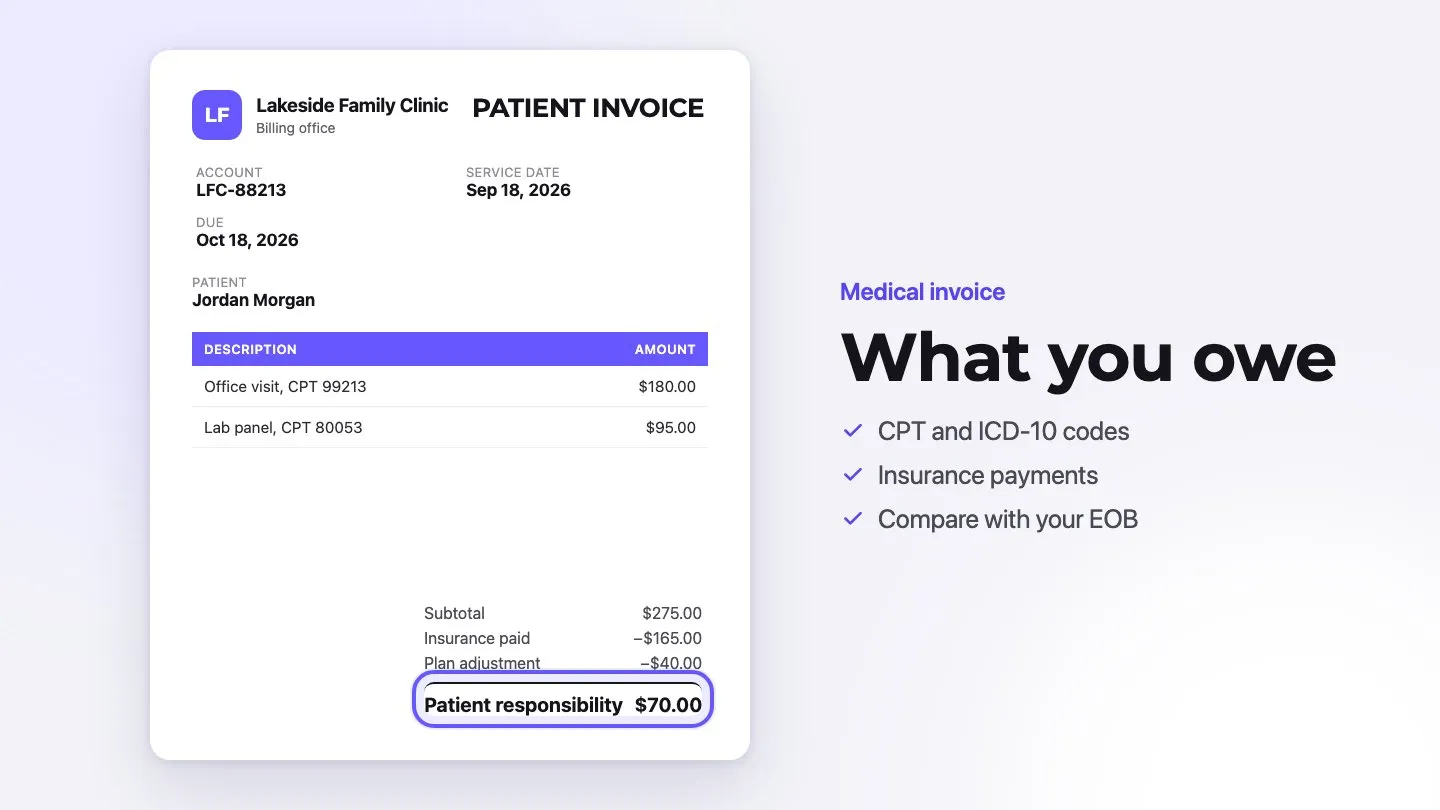
Here is a simple example after insurance has processed the claim:
Lakeside Family Clinic
410 Lake Avenue, Madison, WI 53703
Billing: (608) 555-0118
PATIENT INVOICE
| Item | Amount |
|---|---|
| Office visit, established patientCPT 99213 | $145.00 |
| Rapid strep testCPT 87880 | $38.00 |
- Total
- $183.00
- Contractual adjustment (plan)
- -$52.40
- Paid by Acme Health, Sep 19
- -$100.60
- Balance due
- $30.00
Your share is your $30 office visit copay. Pay online or call billing with questions.
The clinic charged $183. The insurer’s contract allows less, so $52.40 is written off as an adjustment. The plan paid $100.60, and the patient owes the $30 copay.
Medical invoice vs. EOB vs. claim
Three documents describe the same visit, and mixing them up causes most billing confusion:
| Document | Who sends it | To whom | What it is |
|---|---|---|---|
| Claim | Provider | Insurer | The request for payment. Doctors use the CMS-1500 form or its electronic version; hospitals use the UB-04 (CMS-1450). |
| Explanation of Benefits (EOB) | Insurer | Patient | A summary of what the plan paid and what you may owe. CMS: “This is not a bill.” |
| Medical invoice or statement | Provider | Patient | The bill for your share, after insurance. |
Medicare patients get a Medicare Summary Notice instead of an EOB, and Medicare.gov says the same: it is not a bill.
How to read and check your medical bill
- Check your details. Name, date of birth, insurance plan and member ID. A wrong ID can make the claim deny.
- Match the dates and services. CMS advises making sure the services or supplies listed are the ones you received on those dates.
- Compare with your EOB. The amount you owe on the invoice should match “patient responsibility” on the insurer’s EOB for the same date of service. If the invoice arrives first, wait for the EOB.
- Look for duplicates. The same code twice on one date, or a service billed by two providers, is worth a question.
- Ask for an itemized bill if you only got a total. Medicare beneficiaries have a legal right to one: under section 4311 of the Balanced Budget Act of 1997, the provider must send an itemized statement within 30 days of a written request (CMS manual, chapter 6).
- Check your Good Faith Estimate if you paid without insurance. Under the No Surprises Act, uninsured and self-pay patients can get an estimate in advance. If the bill is at least $400 more than the estimate, you can dispute it within 120 days of the initial bill (CMS). The No Surprises Help Desk is at 1-800-985-3059.
- Call the billing office before you pay anything you do not understand. Note who you spoke to and when.
What adjustments, copays and balances mean
- Charge: the provider’s list price for the service.
- Adjustment: a reduction that is not a payment, usually the contractual write-off between the charge and the plan’s allowed amount. You do not owe it.
- Insurance paid: the plan’s payment to the provider.
- Copay: a fixed amount you pay for a type of visit.
- Coinsurance: your percentage of the allowed amount after the deductible.
- Deductible: what you pay each year before the plan starts sharing costs.
- Balance due: charge minus adjustments minus payments. This is what the invoice asks you to pay.
How to spot a fake medical bill
A bill for care you don’t recognize can be a billing mistake, a sign of medical identity theft or a scam. The FTC’s guidance on medical identity theft lists warning signs, including a bill or EOB for services you did not get and a debt collector calling about medical debt you do not owe. Before you pay:
- Make sure you know the provider and had care on the dates shown.
- Compare the bill with the EOB from your insurer. A real bill for insured care should match it.
- Call the provider using the phone number on its official website or your insurance card, not the number or link in the bill.
- Be careful with emails and texts that only contain a payment link. The FTC’s phishing guidance warns about messages that “include an invoice you don’t recognize.”
- If someone used your information to get care, follow the FTC’s steps: get your medical records, report errors to the provider in writing, and report identity theft at IdentityTheft.gov.
For providers: how to create a clear medical invoice
- Bill insurance first, then invoice the patient for the balance the EOB assigns to them.
- Use one line per service with the date, a plain-language description and the code.
- Show the math: charge, adjustments, insurance payments and the balance, so the patient can match it to the EOB.
- Give a due date and easy ways to pay: card, bank transfer, a payment plan if you offer one.
- Add a billing contact with a phone number and hours.
- Protect patient information. Send invoices through a secure channel. In the US, HIPAA rules apply to how covered providers handle health information.
Small practices, therapists and home-care providers can create and send patient invoices with Invoxa’s online invoice generator, including card payments through Stripe. For Excel and Word files, see the medical and healthcare invoice templates. For coding questions, read our medical billing and coding Q&A.
Frequently asked questions
What is an invoice in medical billing?
It is the bill the provider sends to the patient, often called a patient statement. The provider first bills the insurer with a claim; after the insurer pays or denies it, the invoice shows the patient what is left to pay.
What does "adjustment" mean on a medical bill?
An adjustment lowers the charge without a payment. The most common one is a contractual adjustment, the difference between the provider's list price and the amount your insurer's contract allows. You do not owe adjusted amounts.
Is an Explanation of Benefits (EOB) a bill?
No. The EOB comes from your health plan and shows what it paid and what you may owe. CMS says plainly: "This is not a bill." Wait for the provider's invoice, then check that the two match.
How can I spot a fake medical bill?
Check that you know the provider and that the dates and services match care you actually received and your insurer's EOB. Call the provider on a number from its official website, not from the bill. The FTC lists bills for services you did not get as a warning sign of medical identity theft.
Can I ask for an itemized medical bill?
Yes, you can always ask the provider's billing office for one. For Medicare patients it is a legal right: a provider must send an itemized statement within 30 days of a written request.
What is a medical receipt?
A receipt confirms that you paid. It shows the amount, date and payment method, and often the services it covers. Keep receipts for insurance reimbursement, flexible spending or health savings accounts, and taxes.