Seed Fundraising: How to Secure Early-Stage Investment
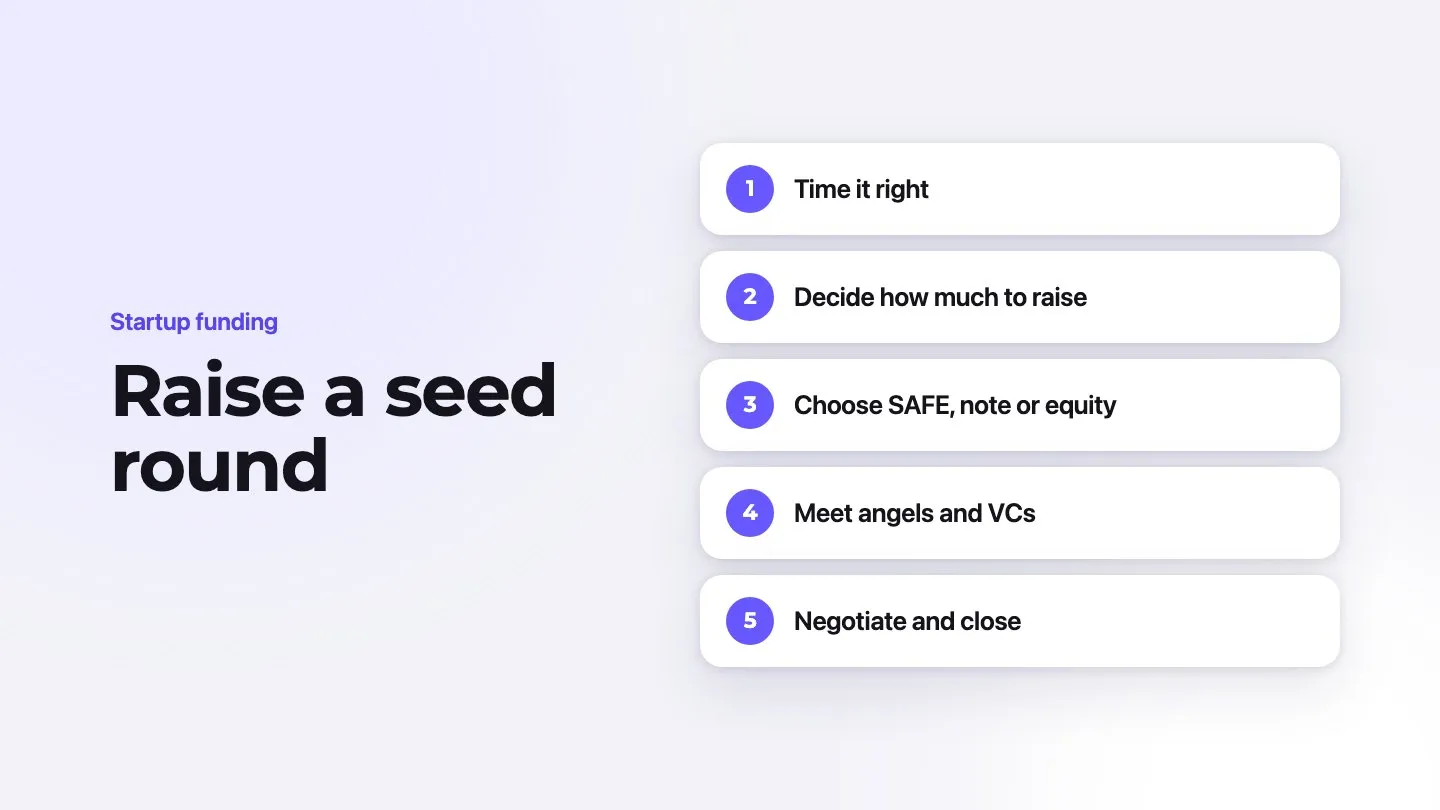
Here’s the no-BS playbook you’ll actually need in the fundraising trenches, cutting through the noise with strategies that work in the real world.
Why External Funding Matters
Let’s get real—without rocket fuel (capital), most moonshot-worthy ventures never leave the launchpad. The cash needed to scale a startup with hockey-stick growth ambitions typically dwarfs what you and your college buddies can scrape together. This guide is specifically about high-velocity companies built for scale—the kind that need to burn significant capital upfront to capture market share before the window of opportunity slams shut.
Sure, there are unicorn stories about bootstrapped successes that never took a dime of outside money. They make for great conference talks, but they’re outliers, not the playbook. Many solid businesses can grow organically without venture backing—your local bakery or accounting firm doesn’t need Series A funding—but that’s not the growth trajectory we’re mapping here.
Cash isn’t just keeping the servers running—it’s your competitive moat. With a war chest in the bank, you can poach that 10x engineer from Google, grab TechCrunch headlines when it matters, blitzscale your customer acquisition while competitors are pinching pennies, and build out a sales machine that turns your startup into a proper revenue-generating beast.
Here’s the good news: VC funds still hold large amounts of dry powder (uninvested capital). The bad news? Fundraising still sucks. It’s a full-contact sport that will test your resilience, storytelling chops, and emotional fortitude. Most founders describe fundraising as “getting repeatedly punched in the face while maintaining perfect composure.” You’ll hear “no” more times than a toddler at bedtime. But timing this pain train right can make all the difference.
The Optimal Timing for Fundraising
VCs pull the trigger when three stars align: they buy into your narrative (the “why now” story), they believe your team can execute (the “who”), and they’re convinced the prize is big enough to matter (the TAM, or total addressable market). When you’ve got these three cylinders firing, it’s time to gas up your fundraising engine.
If you’re a second-time founder with a successful exit under your belt, sometimes your napkin sketch and reputation are enough to unlock checkbooks. The rest of us mere mortals need the “holy trinity”: a crystal-clear value proposition, a working product that doesn’t crash during demos, and some level of user traction that proves you’re not just building a solution looking for a problem.
But investors didn’t build their portfolios on possibilities alone—they need proof points that de-risk their bet on you. A slick demo might get you a second meeting, but it rarely gets you a term sheet. What moves the needle is evidence of product-market fit and growth metrics that suggest you’ve found a wound that’s bleeding badly enough that customers will pay for your bandage.
The optimal fundraising moment hits when you’ve nailed your ICP (ideal customer profile), shipped a product that solves their hair-on-fire problem, and started seeing the kind of traction that makes investors’ FOMO kick into overdrive. What’s “good enough” traction? There’s no single bar, but Paul Graham has written that a good growth rate during Y Combinator is 5–7% a week, and 10% a week is exceptional (“Startup = Growth”). Clear unit economics help too, and so does being “ramen profitable”—earning just enough to cover the founders’ living costs.
How Much Cash to Grab
In an ideal world, you’d raise enough runway to hit escape velocity (profitability), making future fundraising optional rather than existential. Being default alive, not default dead as investors call it, is the ultimate power position. It means you control your destiny when the VC spigot inevitably tightens during market corrections.
Reality check: if you’re building anything with atoms, not just bits (hardware, biotech, advanced materials), you’re probably looking at multiple rounds before reaching the promised land of positive cash flow. For these capital-intensive plays, the game is securing enough fuel to hit your next inflection point—that “holy crap” milestone that makes the next round of investors scramble to get into your cap table. Budget for 12-18 months of runway, knowing that fundraising itself will eat 3-4 months of your life when the time comes.
Setting your fundraising target is a delicate balancing act between giving yourself enough runway to hit meaningful milestones, passing the sniff test with savvy investors, and not giving away the store in dilution. Landing a seed round with only 10% dilution would put you in the fundraising hall of fame; many seed rounds sell somewhere around a fifth of the company. Venture far beyond 25% and alarm bells should ring—you’re setting yourself up for crippling dilution in later rounds, potentially becoming an employee in your own company by Series B.
Whatever number you land on, it needs to sync with a credible, bottoms-up operational plan. VCs can smell a made-up forecast from a mile away. They want to see that your ask is tied to specific growth milestones, not just “here’s a big number that sounds impressive in TechCrunch.”
Pro tip: build a “sliding scale” fundraising model with multiple scenarios—the “ramen budget,” the “reasonable budget,” and the “rocket ship budget.” This shows investors you can execute regardless of whether you raise your full target or just a fraction. Make it clear that the amount you raise affects your velocity, not your destination—you’re getting to the promised land either way, just faster with more capital.
One practical approach to determining your optimal initial funding amount is calculating how many months of operation you wish to finance. Start from the fully loaded monthly cost of each team member (salary, taxes, benefits, equipment and office). If that’s $15,000 a person—an assumption Y Combinator’s seed guide used for US tech hubs, so use your own local figure—an 18-month runway for a team of five needs roughly 15,000 × 5 × 18 = $1,350,000.
This calculation equips you with a compelling response to the inevitable question: “How much are you raising?” You can confidently state how many months of runway you’re raising for and the range of money that requires. Providing multiple scenarios allows you to present different growth trajectories based on various fundraising outcomes.
The sticker price on early-stage rounds varies wildly depending on your geography, sector, and team pedigree, from a few hundred thousand dollars to several million. Seed rounds have grown over the years as large funds moved downstream, and the “pre-seed” category emerged to fill the gap.
Financing Structures: Know Your Weapons
Much as we’d love to tell you venture financing is straightforward, that would be like saying quantum physics is “basically just math.” The legal architecture of these deals can significantly impact your future, so consider this your crash course in not getting screwed.
The venture financing game typically follows a predictable cadence of capital infusions, each with its own fancy label. You’ll start with seed (the money that gets you from idea to evidence), then progress through Series A (scaling what works), Series B (pouring gasoline on the fire), Series C (expanding into adjacent markets), and beyond until you either ring the bell at NASDAQ or hand the keys to an acquirer.
This isn’t a required sequence—some overachievers skip straight to Series A, while others might need a “pre-seed” or “bridge round” to navigate choppy waters. We’re focusing exclusively on that critical first institutional money that transforms your nights-and-weekends project into a real company with a fighting chance.
In today’s ecosystem, most seed deals no longer involve actually setting a company valuation or issuing stock certificates right away. Instead, Silicon Valley and other tech hubs have embraced financial instruments that kick those complicated questions down the road—primarily convertible debt and SAFEs (Simple Agreements for Future Equity).
Convertible Debt: The Original Financial Hack
Convertible debt is essentially a loan with an identity crisis—it walks like debt but dreams of becoming equity. This financial instrument includes a principal amount (how much cash the investor is forking over), a modest interest rate (mostly symbolic, since it usually converts along with the principal), and a maturity date (when, theoretically, you’d have to pay it back, though in practice these often get extended).
The secret sauce here is that nobody actually expects repayment. Instead, these notes are designed to “convert” into equity shares when you raise your next priced round, typically a Series A. The key terms you’ll negotiate are:
- The Cap — Think of this as your startup’s “maximum valuation” for these early investors, regardless of how hot your Series A becomes. If your convertible note has a $5M cap but you raise your Series A at a $10M valuation, these early believers still get their shares priced as if the company were worth $5M. It’s their reward for taking on extra risk.
- The Discount — This is the percentage reduction early investors get off your future priced round. A standard 20% discount means if your Series A shares cost $1, convertible note holders pay $0.80 for the same share. Some notes have both a cap AND a discount, with investors getting whichever gives them the better deal.
These features are the investor’s “early bird special”—their compensation for backing you when you were little more than a pitch deck and a prayer. The terms are always negotiable, but remember that money with too many strings attached can be worse than no money at all.
SAFE Agreements
The SAFE, introduced by Y Combinator in 2013, has largely superseded convertible debt at accelerators. A SAFE functions similarly to convertible debt without the interest rate, maturity, and repayment requirements. The negotiable terms in a SAFE typically consist of the investment amount, the valuation cap, and any applicable discount. YC’s current standard is the post-money SAFE, which makes each investor’s ownership easy to calculate. Review the SAFE documents and user guide on Y Combinator’s website, which includes detailed examples of conversion scenarios.
Equity Financing
An equity round involves establishing a company valuation and consequently a per-share price, followed by issuing and selling new company shares to investors. This approach invariably proves more complex, costly, and time-consuming than implementing SAFEs or convertible notes, explaining their popularity for early-stage rounds.
To grasp how equity rounds actually work, let’s break down a real-world example: Say you’ve hustled your way to a $1M raise at a $5M pre-money valuation (not bad!), and you have 10M shares floating around.
Here’s the math that determines your destiny:
- Share price: $5M ÷ 10M shares = $0.50 per share
- New shares printed for investors: $1M ÷ $0.50 = 2M fresh shares
- New cap table total: 10M + 2M = 12M shares
- Post-money valuation: $0.50 × 12M = $6M
- Dilution hit to existing shareholders: 2M ÷ 12M = 16.7%
Wait, why isn’t dilution 20% if you raised $1M on a $5M pre-money? This is the kind of fuzzy math that trips up first-time founders. The new investors own $1M worth of a now-$6M company, which is indeed 16.7%, not 20%. Understanding these mechanics can save you significant equity over multiple rounds.
Regardless of your chosen financing structure, utilizing established, industry-standard documentation like Y Combinator’s SAFE offers significant advantages. These documents have gained widespread recognition in the investment community and are designed to balance fairness with founder-friendly terms.
Valuation: The Dark Art of Pricing Your Dream
Picture this: You and your co-founder have built a working prototype, maybe signed up a few thousand beta users, and now you’re trying to attach a dollar figure to this whole operation. What’s your company actually worth? Spoiler alert: there’s no spreadsheet formula that spits out the right answer.
Early-stage valuations are about as scientific as astrology—they’re primarily a function of storytelling, market hype, and founder negotiating leverage. Why does one pre-revenue SaaS startup command a $20M valuation while a seemingly identical one settles for $4M? Because that’s what investors were willing to pay based on their perception of potential upside and FOMO (fear of missing out).
The brutal truth: your company is worth exactly what the market will bear—no more, no less. Your best strategy is usually letting the invisible hand do its thing by getting multiple investors interested and letting competitive dynamics drive up your price. In the absence of a bidding war, find a lead investor you trust to set a fair valuation, then leverage that social proof to bring in others.
Do your homework on comparable companies at similar stages—what valuation did they secure with similar levels of traction? Just remember: don’t get greedy and try to optimize for the absolute highest possible number. The fundraising game is about striking the delicate balance where you:
- Protect enough of your equity to stay motivated (and leave room for future rounds)
- Raise enough cash to hit meaningful milestones
- Offer terms attractive enough that investors see potential for their required returns (early-stage investors look for companies that could return many times their investment)
Seed-stage valuations vary enormously by market and sector, and obsessing over valuation optimization is usually counterproductive. A sky-high valuation creates pressure to match those expectations and can lead to a down round later (the startup kiss of death).
Investor Species: Angels vs. VCs in the Wild
In the fundraising food chain, angels and VCs represent distinct species with different hunting patterns. Here’s the breakdown:
Angels are typically wealthy individuals writing personal checks from their own bank accounts. They’re the freestyle jazz musicians of investing—following their gut, making quick calls, and often investing in people they simply like being around. While some super-angels run sophisticated operations rivaling small VC firms, most are essentially well-heeled hobbyists who can pull the trigger after a single coffee meeting if they dig your vision. The emotional connection often matters as much as your metrics.
VCs, by contrast, are the institutional players—professional money managers investing other people’s cash (their “limited partners” or LPs). They answer to investment committees, manage structured portfolios, and generally need to justify their decisions with more than “this founder has good energy.” Expect a more formalized process with multiple partner meetings, deeper due diligence, and more people weighing in on the decision.
Remember: VCs are flooded with pitches and invest in only a small fraction of the companies they evaluate. If every venture were a carnival game, VCs are trying to find the one ring toss that might return their entire fund, knowing that most of their bets will fail.
The early-stage funding landscape has undergone a radical transformation in recent years. The classic angel-or-VC binary has exploded into a complex ecosystem with new species emerging constantly. “Micro-VCs” and “super-angels” now operate in the white space between traditional categories, often moving with the speed of angels but the rigor of VCs.
How can you connect with investors? If you’re preparing for a demo day presentation, you’ll encounter numerous investors in a concentrated setting. Outside of demo days, warm introductions represent by far the most effective method for connecting with VCs or angel investors. Angels frequently introduce promising companies to their networks. Otherwise, leverage your existing connections to secure introductions. When other options are unavailable, research potential investors and distribute a concise but compelling business summary to as many appropriate prospects as possible.
Crowdfunding Alternatives
An expanding array of alternative funding platforms has emerged, including AngelList syndicates, Kickstarter for product pre-sales, and equity crowdfunding portals such as Wefunder. In the US, Regulation Crowdfunding lets a company raise up to $5 million in 12 months from the public through a registered portal. In exceptional cases, founders have leveraged these platforms as their primary funding source or as compelling evidence of market demand. More typically, they supplement rounds that are substantially complete or occasionally revitalize stalled fundraising efforts.
Engaging with Investors
When meeting investors during a dedicated investor day, remember that your immediate objective isn’t securing commitment—it’s advancing to the next meeting. Investors rarely commit immediately upon hearing your pitch, regardless of its quality.
Several fundamental principles govern investor meeting preparation. First, thoroughly research your audience—investigate their investment preferences and understand their motivations. Second, distill your presentation to essential elements: why your product offers unique value (demonstrations have become nearly mandatory), why your team possesses the precise capabilities required, and why you should collectively pursue building the next transformative company.
Listen attentively to investor feedback. If you can encourage investors to speak more than you do, your probability of securing investment increases dramatically. Similarly, establish authentic connection with investors—this explains the importance of preliminary research. Venture investment represents a long-term commitment, and investors evaluate numerous opportunities. Without personal connection and commitment to your success, investment remains unlikely.
Your identity and narrative presentation significantly influence investor decision-making. Investors seek compelling founders with credible visions supported by tangible evidence validating those aspirations. Develop a presentation style aligned with your personality, then refine it relentlessly.
During investor meetings, balance confidence with humility. Avoid arrogance, defensiveness, or excessive accommodation. Remain receptive to thoughtful counterpoints while advocating for your convictions. Whether you persuade the investor immediately or not, creating a positive impression increases the likelihood of future opportunity.
Finally, never conclude an investor meeting without attempting to advance the process or establishing absolute clarity regarding next steps. Avoid departing with ambiguous expectations.
Negotiating and Finalizing Agreements
Seed investments can typically close rapidly. As previously noted, utilizing standardized documentation with consistent terms, such as Y Combinator’s SAFE, offers significant advantages. Negotiations, when necessary, can then focus on one or two variables, such as valuation/cap and potentially a discount provision.
Investment momentum drives outcomes, but no formulaic approach guarantees momentum beyond presenting a compelling narrative, demonstrating persistence, and conducting thorough groundwork. You may need to meet dozens of investors before securing commitment. However, convincing a single investor provides sufficient initial momentum. Once securing initial investment, subsequent commitments typically accelerate and simplify.
When an investor confirms participation, you approach completion. This stage requires rapid execution following established protocols. Negotiation failures at this point typically reflect founder missteps rather than external factors.
Negotiation Strategies
When entering negotiations with VCs or angels, recognize their typically superior experience in this domain. Consequently, avoiding real-time negotiation generally proves advantageous. Address investor requests after consultation with accelerator partners, advisors, or legal counsel. However, remember that while certain terms may prove objectionable, most requests from credible investors typically reflect reasonable industry standards.
Regarding valuation (or cap) negotiations, numerous factors warrant consideration, including previously completed investments. However, remember that early-round valuation rarely determines venture success or failure. Secure optimal terms consistent with your circumstances—but prioritize completing the transaction!
Once reaching agreement, avoid delays. Secure investor signature and funding immediately. SAFEs have gained popularity partly because their closing mechanics involve simply signing documentation and transferring funds. Once an investor decides to invest, completing the transaction should require minimal time—exchanging signed documents electronically (via platforms like Clerky or DocuSign) and processing wire transfers.
Essential Documentation
Avoid excessive time developing due diligence materials for seed rounds. Investors requesting extensive documentation or financial analysis likely represent partners to avoid. Typically, you’ll need an executive summary and presentation deck for investor meetings and subsequent reference as VCs share with additional partners.
Your executive summary should comprise one or two pages (preferably one) and include vision, product, team information (location, contact details), traction metrics, market size assessment, and basic financial information (revenue, if applicable, and previous/current fundraising).
Ensure your slide deck functions effectively as standalone reference material. Graphics, charts, and screenshots generally communicate more powerfully than extensive text. Consider the deck a framework supporting your more detailed narrative. While no universal format exists, certain elements typically appear in most presentations:
- Company identity — Logo and tagline
- Vision statement — Your most expansive articulation of your company’s purpose
- Problem definition — Customer pain points and challenges addressed
- Customer profile — Target audience characteristics and acquisition strategy
- Solution overview — Your product/service and why current timing is optimal
- Market opportunity — Total Available Market (ideally exceeding $1B) with compelling supporting evidence
- Competitive landscape — Including direct competitors, macro trends, and unique insights
- Traction metrics — Key performance indicators, scaling plans, and customer acquisition strategy
- Business model — Revenue generation mechanisms with actual results, projections, and expectations
- Team composition — Founder backgrounds, relevant expertise, and roles (including visuals and brief biographies)
- Key takeaways — 3-5 critical insights (market scale, product differentiation, growth metrics)
- Fundraising status — Current capital raised and fundraising targets, with optional financial projections and product roadmap (maximum six quarters) illustrating investment impact
FAQs About Seed Fundraising
1. What’s the difference between pre-seed and seed funding? Pre-seed funding typically comes before you have a fully functional product or significant traction, and it’s usually the smaller round. This money helps you build an MVP and find initial product-market fit. Seed funding comes slightly later when you have some evidence your idea works and need more capital to scale your operation, hire key team members, and prepare for a Series A. Pre-seed investors take on more risk and often include friends, family, angels, and early-stage focused micro-VCs.
2. How much traction do I really need before approaching investors? There’s no universal number. For B2C startups, investors look for a growing base of active users who keep coming back (engagement metrics such as DAU/MAU). For B2B startups, a handful of paying customers or pilots with recognized companies provides strong validation. If you’re pre-revenue, show other indicators like a growing waitlist, strong week-over-week growth, or decreasing customer acquisition costs. The key is demonstrating momentum and repeatable customer acquisition.
3. Should I use a SAFE agreement or convertible note for my seed round? SAFEs are typically more founder-friendly since they don’t include maturity dates or accrue interest like convertible notes. They’re simpler documents with fewer terms to negotiate. However, convertible notes might be more appealing to investors in more conservative markets or industries where the SAFE hasn’t gained widespread adoption. If you’re working with accelerators like Y Combinator or investors familiar with Silicon Valley practices, SAFEs are generally the better option as they close faster and have fewer downsides for founders.
4. What’s a realistic timeline for completing a seed fundraising round? From initial outreach to money in the bank, expect the entire process to take 3-6 months. The first investor typically takes the longest to secure (often 2-3 months of meetings and follow-ups), while subsequent investors usually move faster once you have social proof. The actual closing process after verbal commitments can take 2-4 weeks for paperwork, legal review, and fund transfers. Build a 6-month runway buffer before starting fundraising to avoid negotiating with your back against the wall.
5. What is a “cap table” and why is it important for seed-stage companies? A cap table (capitalization table) is a spreadsheet or document that tracks all the equity ownership in your company—including founders’ shares, employee options, and investor stakes. It shows who owns what percentage of your company and how ownership will change with new investments or option grants. Keeping a clean, well-organized cap table is crucial because investors will scrutinize it during due diligence, it affects your ability to offer competitive equity packages to employees, and it reveals potential issues with voting control or excessive dilution. Common cap table mistakes include giving away too much equity too early, creating complicated share classes, or failing to document equity promises made to early team members.