Startup Idea: 10 Steps to Finding and Validating Your Next Big Business
Let’s be honest — most founders have been there. Sitting at a coffee shop, scribbling random business ideas that “feel right” without any real market validation. It’s the entrepreneur’s version of throwing darts blindfolded, and passion without validation leads to expensive lessons.
That’s why this is a no-BS guide for finding business ideas that actually have a fighting chance. No more building in isolation! Whether you’re bootstrapping your first venture or innovating within an established company, follow these practical steps and you’ll walk away with a shortlist of tested ideas worth pursuing.
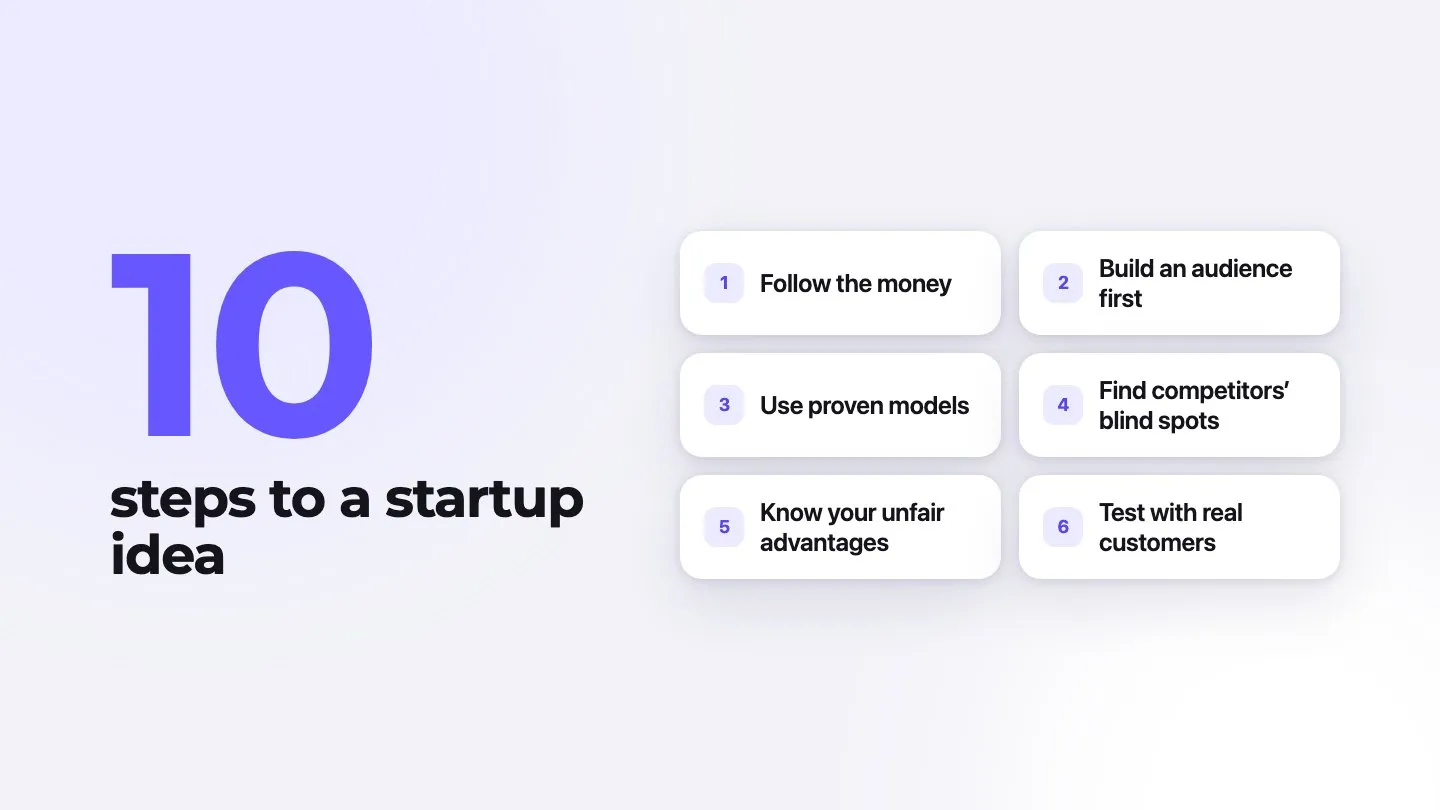
The 10-Step Idea Discovery Journey
- Find your tribe and follow the money
- Build your audience before your product
- Stand on the shoulders of proven models
- Learn from competitors’ blind spots
- Inventory your unfair advantages
- Get a reality check from someone who’s been there
- Go where the growth is
- Plug into existing success stories
- Mix, match and prioritize your best shots
- Test with real customers, fast
Here’s each step, with practical advice.
1. Find Your Tribe and Follow the Money
Why start with your people? Because too many entrepreneurs build in isolation, only to launch to crickets.
Here’s the reality: Once you have a product, you’ll need customers. And finding those customers from scratch, through paid ads alone, is brutally expensive.
When you’re part of an existing community:
- You understand their language, pain points, and search behavior (making your SEO and Google Ads infinitely more effective)
- You know exactly how to target them on platforms like Facebook and LinkedIn (so less of your ad budget is wasted)
- You’ve already built relationships for direct outreach (no cold calling strangers)
Building software keeps getting cheaper, while paid attention keeps getting more expensive. Starting with a community is just smart business.
Finding Your Tribe: Look for growing communities on Reddit, active Discord servers, Facebook Groups, or specialized forums. Aim for communities big enough to validate ideas, but not so massive that you can’t stand out.
Next — follow the money. What does your tribe actually spend on? Not what they say they want, but what they actually pull out their credit cards for.
For example, if you explore the cycling space, road cycling communities will show you members spending money on:
- Bike upgrades
- Premium accessories
- Event registrations
- Coaching/training plans
- Travel to cycling destinations
Noting what people buy, and roughly how much they spend, helps you size the market and spot underserved spending categories with high margins.
Your Turn: Join 2-3 communities you’re genuinely interested in. Spend two weeks observing conversations. Make a spreadsheet tracking what members frequently purchase, approximate costs, and pain points they mention around these purchases.
2. Build Your Audience Before Your Product
Building an audience first is a real unfair advantage. Think about it: Glossier grew out of the beauty blog Into the Gloss, and Robinhood built a waitlist of around a million people before launching its app.
Today, every business is becoming a media company at its core. The battle for attention precedes the battle for wallet share every single time.
Launching cold means paying for every user. Launching to an audience you’ve built through content means your first customers are already waiting, and your acquisition cost drops sharply just by flipping the order of operations.
The media-first approach lets you:
- Test messaging and positioning in real-time
- Build trust before asking for money
- Get invaluable feedback to shape your product
- Create a ready-made customer base
Real Example: Morning Brew started as a newsletter for business students in 2015 and grew to millions of subscribers; in 2020 Insider bought a majority stake at a reported valuation of about $75 million.
Your Turn: Brainstorm three media assets you could create for your target audience:
- A weekly newsletter focusing on industry trends
- A podcast interviewing thought leaders
- A data-driven report published monthly
Choose one and outline your first month of content. Don’t worry about monetization yet — focus on providing genuine value.
3. Stand on the Shoulders of Proven Models
Here’s a secret that should help you sleep better: you don’t need a revolutionary idea to build a successful business. Facebook wasn’t the first social network, and Google wasn’t the first search engine.
Innovation rarely means inventing something from scratch. It usually means adapting what works elsewhere to a new market, audience, or distribution channel.
Call it “proven model arbitrage” — taking business models that work in one context and adapting them for another. It dramatically reduces your risk while still creating massive value.
Subscription models like Dollar Shave Club’s, for example, have been copied for many other products and countries with localized products and messaging — winning not by inventing the model, but by executing it well in an underserved market.
Where to Find Proven Models:
- ProductHunt — Browse trending products across categories
- TrendWatching — Global consumer trend insights
- Exploding Topics — Data-driven trend discovery
- Indie Hackers — Transparent business journeys
Your Turn: Identify three successful business models from other markets that could be adapted to your target audience. For each one, note:
- What makes it successful in its original market
- Why it might work for your audience
- What adaptations would make it more relevant
4. Learn from Competitors’ Blind Spots
Every successful company has weaknesses — blind spots they’re either unaware of or unable to address because of their size, target audience, or business model. These gaps are golden opportunities.
Large marketplaces, for example, are built for the average customer. Specialist platforms for corporate housing have grown by serving business travelers, whose needs (invoices, longer stays, consistent standards) a general platform handles less well.
The best part? You don’t need to compete head-on with giants. You just need to find the segment they’re neglecting.
Tools for Competitive Analysis:
- SimilarWeb — Traffic analysis and user behavior
- SpyFu — Competitor keyword and ad strategy
- Facebook Ad Library — Review competitor advertising
- Sensor Tower (which absorbed data.ai, formerly App Annie) — Mobile app intelligence
- G2 and Capterra — Read user reviews to find pain points
Your Turn: Choose one major player in your target market. Spend an hour reading their negative reviews on G2, Trustpilot, or social media. Identify three recurring complaints or unaddressed needs. For each one, brainstorm how you could create a focused solution.
5. Inventory Your Unfair Advantages
We each have a unique combination of skills, experiences, and connections that give us advantages in specific areas. Call these your “personal moats” — advantages that can’t be easily copied or purchased.
Your unfair advantage probably isn’t technical genius. More often it’s an unusual combination of experience, industry connections, and genuine enthusiasm for solving a specific problem that nobody else seems interested in tackling.
Your unfair advantage might be:
- Domain expertise from years in a specific industry
- A network of potential customers or partners
- Technical skills in an emerging field
- Cultural insights about an underserved community
- Personal experience with a problem worth solving
The intersection of your skills, interests, and market opportunity is where magic happens.
Your Turn: Answer these questions honestly:
- What could you happily work on every day for the next five years?
- What skills have people consistently paid you for?
- What do friends and colleagues come to you for advice about?
- What problems do you have firsthand experience with?
- What communities do you have authentic access to?
Map these on paper to find interesting overlaps. These are your zones of opportunity.
6. Get a Reality Check from Someone Who’s Been There
The right mentor can save you years of expensive trial and error, and spot a fatal problem, such as a legal issue, before it sinks your startup.
Having someone who’s walked the path before you isn’t just helpful — it can be the difference between success and failure.
The key is finding advisors with specific, relevant experience — not just generic business success. Someone who built and sold a SaaS company can probably help your SaaS startup, but might have little valuable insight for your D2C brand.
Finding the Right Mentors:
- SCORE — Free business mentorship program
- Paid expert-call platforms — Book time with specialists by the hour
- Industry conferences — Connect with speakers and leaders
- LinkedIn — Search your extended network for introductions
- Y Combinator Startup School — Free expert guidance
Your Turn: List five potential mentors who have experience directly relevant to your business ideas. For each person, identify:
- How they could specifically help you
- What value you could offer them in return
- How you might get an introduction
Remember, the best mentorship relationships are two-way streets, not charity cases.
7. Go Where the Growth Is
Size matters in business, particularly if you have ambitions beyond lifestyle entrepreneurship. As investor Marc Andreessen wrote in his 2007 essay “The only thing that matters”: “In a great market — a market with lots of real potential customers — the market pulls product out of the startup.”
A superior product in a stagnant niche can hit a ceiling early, while a merely adequate product in a fast-growing segment can grow quickly.
The lesson? Market selection often outweighs execution in determining your ceiling.
Examples of markets that many analysts expect to keep growing (check current data before relying on any forecast):
- Mental wellness tech and services
- Alternative protein and plant-based foods
- Tools for remote and hybrid work
- Sustainable home goods
- Personalized nutrition
Tools for Market Analysis:
- Statista — Market research and forecasts
- IBISWorld — Industry reports and analysis
- CB Insights — Trend analysis and forecasting
- Crunchbase — Investment tracking by sector
Your Turn: Identify three growing markets that interest you. For each market:
- Estimate the current market size
- Research the projected 5-year growth rate
- List the major players and their strengths/weaknesses
- Identify at least one underserved segment or need
8. Plug into Existing Success Stories
Sometimes the smartest move isn’t building a standalone business but creating something that enhances an existing ecosystem. Call it the “remora strategy” — attaching to a larger organism in a symbiotic relationship.
When Salesforce launched its AppExchange, clever entrepreneurs built specialized tools on top of the platform. Some grew into substantial businesses by solving specific problems for Salesforce users. They leveraged the giant’s distribution and existing customer base while focusing narrowly on underserved needs.
Successful businesses have been built on:
- Shopify’s app ecosystem
- WordPress plugins
- Zoom app marketplace
- Amazon’s seller ecosystem
- HubSpot’s app platform
The beauty of this approach is that you get instant distribution and a clearly defined customer base. Your success becomes tied to the platform’s success.
Your Turn: Identify three thriving platforms or ecosystems where you could add value. For each one:
- Research the most popular third-party additions
- Identify gaps or underserved needs
- Brainstorm a product that would enhance the core platform
- Estimate the size of the user base you could potentially reach
9. Mix, Match and Prioritize Your Best Shots
By now, you should have generated numerous potential business ideas. The challenge shifts from idea generation to prioritization. This is where objective evaluation becomes crucial.
When you’re choosing between several promising concepts, a simple scoring system helps. Score each on:
- Market size and growth trajectory
- Competitive intensity
- Initial investment required
- Your personal interest and expertise
- Revenue potential and scalability
- Time to first dollar of revenue
This framework forces you to be honest about which opportunity truly deserves your time and resources.
Prioritization Framework:
- Rate each idea from 1-10 on the factors above
- Weight the factors based on your personal priorities
- Calculate a final score for each opportunity
- Be ruthlessly honest about your evaluation
Don’t just chase the highest potential return. Factor in your personal interests and strengths. A business that aligns with your passions will sustain you through inevitable challenges.
Your Turn: Create a simple scoring system for your ideas. Evaluate each one objectively, then ask:
- Does this idea genuinely excite me?
- Do I have unique advantages in this space?
- Can I envision working on this for the next 3-5 years?
- Does the opportunity size justify the effort required?
Choose the highest-scoring idea that also passes these gut-check questions.
10. Test with Real Customers, Fast
Ideas are worthless without execution and validation. The final — and most crucial — step is getting your concept in front of real customers as quickly as possible.
Perfectionism is a trap: it’s easy to spend nine months building before showing anything to customers, only to find you’ve built something nobody wanted. Try a strict 30-day rule: get something tangible in front of potential customers within a month of committing to an idea.
Your Minimum Viable Product (MVP) doesn’t need to be polished or complete. It just needs to test your core value proposition with real users.
Quick MVP Options:
- Landing page with clear value proposition and waitlist signup
- Concierge service (manually delivering the value your product would automate)
- Wizard of Oz prototype (interface looks automated but you’re doing work manually)
- Simple pre-order campaign
- Crowdfunding campaign on Kickstarter or Indiegogo
- Single-feature prototype focusing on the core value
The goal isn’t perfection, it’s learning. Each interaction with potential customers will refine your understanding of the problem and solution.
Tools for Rapid Testing:
- Webflow or Carrd — Build landing pages without coding
- TypeForm — Create interactive forms and surveys
- Gumroad — Sell digital products with minimal setup
- Substack — Launch a paid newsletter
- Stripe — Accept payments with simple integration
Your Turn: Outline a plan to create and launch a basic version of your chosen idea within 30 days. Focus on testing your core value proposition with minimal investment. Set specific metrics that would indicate sufficient interest to continue development.
5 Frequently Asked Questions
1. What exactly is a “personal moat” and how do I identify mine?
A personal moat is your unique, defensible advantage that competitors can’t easily replicate. Unlike traditional business moats (patents, economies of scale, network effects), personal moats are individual to you. To identify yours, look for unusual combinations of skills, experiences, and relationships you’ve built. For example, deep knowledge of e-commerce logistics combined with connections in the sustainable packaging industry and fluency in three languages is an intersection few competitors share. Make a Venn diagram of your specialized knowledge, network access, and personal experiences to find your own distinctive combinations.
2. How do I validate a business idea if I have almost no budget?
Start with zero-cost testing methods: conduct 15-20 customer interviews, create a landing page using free tools like Carrd, and build a waitlist to gauge interest. Launch a fake-door test by advertising a non-existent product and measuring click-through rates. Join relevant communities and share your concept for feedback. Set up a simple Google Form to collect pre-orders with “pay later” options. The key is measuring actual behavior (clicks, signups, commitments) rather than opinions. Many ideas can be validated for the cost of a domain name and a few free tools. If you run a fake-door test, tell people who sign up that the product isn’t available yet.
3. Is bootstrapping or seeking funding better for a first-time entrepreneur?
The right approach depends entirely on your business model and personal goals. Bootstrapping gives you complete control and forces capital efficiency, but limits your growth speed. For businesses with low initial costs, predictable revenue, and modest growth trajectories (like service businesses or niche SaaS), bootstrapping often makes more sense. Funding becomes necessary when you’re entering a winner-takes-most market, facing well-funded competitors, or building something with significant upfront development costs. Many founders find that bootstrapping teaches better fundamentals, while funding helps them scale faster once they have product-market fit.
4. How do I know when to pivot versus when to persevere with my original idea?
The decision to pivot should be data-driven, not emotional. Set clear metrics before you launch: conversion rates, customer acquisition costs, retention rates, and user engagement benchmarks. If you’re consistently falling short despite good-faith optimization efforts, it’s time to consider a pivot. Look for “bright spots” – unexpected positive signals that might indicate a more promising direction. For example, if your fitness app isn’t growing overall but a specific feature has passionate users, that feature might become your new core offering. Follow user behavior rather than your own assumptions.
5. How important is timing when launching a new business?
Timing is everything. Too early and you’ll waste resources educating an unready market; too late and you’ll face entrenched competitors. The sweet spot is entering just as adoption is beginning to accelerate – what Geoffrey Moore calls “crossing the chasm” from early adopters to mainstream customers. Look for indicators like growing search volume, increasing media coverage, and early competitive entrants gaining traction. Monitor funding in adjacent spaces and technology cost curves that might enable new business models. The best timing is often when customer pain is high and alternative solutions exist but are cumbersome, expensive, or fragmented – creating a perfect opportunity for an elegant, integrated solution.